
I Don’t Like Losses, Sport
We have news you can use today on the subject of the most powerful, inevitable, fearsome, mysterious, taboo, and untouchable four-letter word in the advanced bioeconomy lexicon.
Risk.
The problem of Investor risk is ridiculously easy to understand and ridiculously hard to solve. If you think back to your own 401(k) or IRA for a second, you’ll understand risk tolerance among financial investors in a jiffy.
Financial investors will tolerate very short-term cases of marginally sub-par returns and they have no tolerance at all of losses.
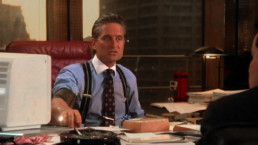
As Michael Douglas, in his Oscar-winning turn as Gordon Gekko in Wall Street, elegantly explained it:
“I don’t like losses, sport. Nothing ruins my day more than losses. Now you do good, you get perks, lots and lots of perks.”
The poor distribution of technology risk is a market failure, especially corrosive in the bioeconomy because risk concentrates like a hurricane and blows down those least able to bear it, like a bully picking out a mark on the playground.
And risk induces panic and suffocation long before it induces death, which is one reason why the Valley of Death is so unimaginably painful to ventures and the people in them. Chilling early-stage venture investing far more effectively and absolutely than the absence of good deal flow.
What’s to protect the bondholders? The technology risk insurance program.
The remedy
Recently, Fulcrum BioEnergy raised $150 million in bond financing for its Sierra BioFuels project, which will convert up to 175,000 tons of municipal solid waste per year into more than 10 million gallons of low-carbon synthetic crude oil, beginning in early 2020. More on Fulcrum’s progress here — and our most recent Multi-Slide Guide is here.
Fulcrum’s existing investors include US Renewables Group, Rustic Canyon Partners, United Airlines, Waste Management, BP, and Cathay Pacific. Their strategic equity capital is at risk — as it should be.
“There’s a lot that’s special about the Fulcrum project,” New Energy Rick CEO Tom Dickson told The Digest. “They have Abengoa as an EPC, and despite what has happened to the corporate paren, Abengoa’s core US EPC unit is strong. They have offtake, great management, irreplaceable equity partners. But it’s not GE standing behind a technology with a performance agreement. There’s a perceived technology risk.
So, who’s measuring that risk in order to efficiently spread it. Turns out, not many.
“Each party has a focus on the risk they have a mandate to assume,” Dickson noted. “Lenders have a mandate to take credit risk, and some market risk. But they are not really into assuming technology risk. Because of that, when it comes to the technology process risk, they are not trying to understand that, and someone has to do that to get first commercials financed, and put capital behind that assessment.”
How’d that “first of kind” project get done? For one thing, Fulcrum brought in New Energy Risk, an affiliate of global insurance giant XL Catlin.
New Energy Risk is a specialty insurance technology company that acts as an effective bridge between new technology innovators, insurers and lenders. It was founded in 2010 to provide complex risk assessment and is part of XL Innovate, an insurance technology venture firm. It’s not a small potatoes thing. The firm has helped its customers gain over $1 billion in financing for renewable energy and new technology deployments.
In this case, New Energy Risk developed a custom solution, backed and provided by XL Catlin (the global brand used by XL Group Ltd’s insurance and reinsurance companies which provide property, casualty, professional and specialty products around the world).
What happened?
“We start with the engineering data,” explained NER’s Jon Cozens, “ and we end up with actuarial output. From the engineering data we are creating a model and looking at failure modes, and the impact on financing and the risk position. In the event of a failure, we ask, how long will it take to alleviate, is the capital there to handle it, and could the timelines impact loan covenants.
“We step in when there is underperformance,” Dickson added, “when the project has run out of alternative means — warranties, it’s own cash — and the failure is due to the technology. Not because of a hurricane, but because of the science; you turn it on, it doesn’t work or at a low percentage of nameplate and because of that , in default of a loan covenant. We alleviate that shortfall.”
Every financing is different
Sometimes the risk freak-out factor focuses on long-term performance, sometimes around start-up and commissioning.
To complicate matters, every project is so darn different. It’s not as simple as: here’s a wind turbine, here’s the standard power purchase agreement, here are the wind curves. The feedstocks are different, the molecules vary, the technologies are unique, the offtake agreements are one-offs, the lenders are not the same, some bonds are rated and others are not, the loan periods don’t line up, the covenants change with every deal.
Dickson explains, “it depends on the policy. if it is short term and responding to risk around completion and commissioning, for us we’re looking really at moving stuff through the pipes, and what are the failure modes, and how do you recover from those. Does it mean adding a unit or redesigning — and does the project have enough time to fix it?”
“In a 10 year policy where we are looking at failure at any time during amortization when it falls below X. By then, the pipes have been figured out, and it is about long-term science, and becomes more about reliability than the expected efficiency. Also, we do work, actively with the USDA loan guarantee program. 9003 loan guarantees require an EPC wrap, and while a lot of EPCs do will wrap completion and delay, it’s been tough relating to the technology itself. Some are successful, some get there some do not. We’ve been working in that area as well.”
So, it’s complex and time consuming.
“It can take 3–4 months for our work,” Dickson noted. “But we’re never the long pole in the tent when it comes to timelines.”
The best projects survive
“If we can structure around the risk,” Cozens told the Digest. “There are going to be fewer failures and more successes. But we want to help the strong projects and keep the projects not yet ready on the back burner. Even if we structured our way out of a loss [from a single project], we all need to grow the capital base, and that means not just doing projects for the sake of it and making money for ourselves, but identifying and supporting the best projects.”
And Fulcrum fits that mould. As Dickson eplained, “Fulcrum is showing what is possible in the waste-to-fuel space, and doing it at unprecedented scale. We look forward to working with them on more projects in the years to come.”
Best of breed, multiple projects. Terms that were in the “future milestones” part of a corporate slide desk, say, five years ago. Today, we’re seeing the survivors from a culled flock beginning the breakout from the Valley of Death.
As Cozens noted, “The winners in the market are survivors and for a reason,”
Originally published at www.biofuelsdigest.com on December 11, 2017.
$500M in Renewable Energy Projects
Insurtech company hires Chief Science Officer to deepen scientific expertise of emerging energy-related technologies
MENLO PARK CALIF – “Today, New Energy Risk, a global pioneer in creating insurance policies for renewable, high-efficiency energy developers and new technology producers, announced that its customers have secured a total of $500M in financing to support such energy projects.
Since its founding, New Energy Risk has underwritten production insurance for over $250 million in financing for fuel cell and waste-to-energy projects, including a 65MW Bloom Energy deployment. An additional $250 million is set to deploy this year, ranging from biomass to solar to energy storage. Using its modeling technology, New Energy Risk is fundamentally improving the economics behind alternative energy deployments, making them more cost competitive and providing certainty of output for customers, owners, and financiers.
Transitioning a new technology from science (proving the fundamentals) to engineering (implementing it in the field) can be expensive, time consuming, and complicated. This transition comes with high technical risk, and such risks have made it difficult for renewable energy projects to gain access to favorable financing terms. However, an insurance policy that guarantees output would significantly reduce the risk for buyers and funders, who otherwise want to adopt and support sustainable practices. Such policies did not exist, until now.
New Energy Risk offers customized insurance solutions for large-scale energy projects by accurately quantifying the risks and uncertainty associated with renewable energy projects for the very first time. This allows insurers to underwrite such projects, unlocking lower interest rates and energy costs over the long term. New Energy Risk’s unique offering lies in its algorithmic approach: a techno-economic risk model that combines analytics around scientific validity, engineering feasibility, project financials, and actuarial science.
New Energy Risk is led by experts in actuarial science, energy technologies, engineering, and financial modeling. In order to continue deepening its scientific understanding of new renewable energy technologies, the company has added Dr. Brentan Alexander, an expert in waste-to-energy processes, thermochemistry, and electrochemistry, as the firm’s Chief Science Officer. Dr. Alexander is a graduate of MIT and Stanford, serial entrepreneur, and leading researcher in the field of the clean conversion of carbon-based fuels. New Energy Risk has also promoted Jon Cozens, its Managing Director, to Chief Commercial Officer, to add focus on the company’s business development, partnerships, and transaction execution.
“We are thrilled to be working with incredible partners such as XL Catlin and a panel of leading global reinsurers, as well as cutting-edge renewable energy companies from around the world. Together, we have promoted over $500 million worth of large-scale energy deployments and we are experiencing unprecedented interest from customers seeking to deploy new forms of clean energy. In response, we have grown our team, both in size and expertise, with the addition of Dr. Alexander as Chief Science Officer and the expansion of Jon Cozens’ role as Chief Commercial Officer,” said Tom Dickson, CEO of New Energy Risk.
“New Energy Risk is the only dedicated, reliable source of performance analysis and underwriting for renewable energy and industrial biomass projects,” said John May, Managing Director at leading investment firm, Stern Brothers & Co., and Co-Head of the its Cleantech Energy and Infrastructure Group. “Their expertise and capacity for performance insurance is a key ingredient in successfully financing large deployments around the world. We look forward to continue working with them to accelerate the adoption of these new energy technologies.”
About New Energy Risk
New Energy Risk is a provider of innovative data analytics and financial risk transfer solutions to the renewable energy industry worldwide. It was founded in 2011 to serve as a risk assessor and intermediary between clean-energy innovators and insurers.